Wauvel
Finance 101

Fixed vs. variable: why your cost structure decides your risk
← All posts
By Blake EkelundOctober 7, 2026 · 7 min read

Two competitors do $1.2m of revenue and $120,000 of profit. One runs a mostly fixed cost base — salaried staff, owned equipment, a long lease. The other subcontracts, rents, and pays commission.

On this year's numbers they look identical. They are not remotely the same business, and a 20% swing in revenue in either direction will make that obvious.

Operating leverage, both ways

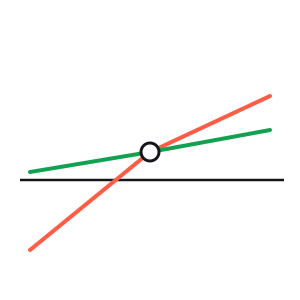
A fixed cost does not move when volume does. So once fixed costs are covered, almost all of each additional sale drops to profit — and below that point, almost all of each lost sale comes straight out of it.

Same business today, 20% either way
RevenueMostly fixedMostly variable
$1,440,000 (+20%)$336,000$192,000
$1,200,000 (plan)$120,000$120,000
$960,000 (−20%)−$96,000$48,000
Identical at plan. In a good year the fixed-cost business earns nearly three times as much; in a bad one it loses money while the variable-cost business stays profitable. Neither structure is correct - they suit different worlds.

The fixed-cost business has higher upside and a real chance of a loss. The variable-cost business gives up profit in good years to buy survivability in bad ones. That is the entire trade, and it should be a deliberate choice rather than an accident of how you happened to grow.

Choose your structure from your volatility

The right answer follows from how predictable your revenue is.

  • Stable, contracted revenue. Lean fixed. Subscription bases, long-term contracts and repeat maintenance work can carry fixed costs safely, and the operating leverage is a genuine advantage.
  • Lumpy or project revenue. Lean variable. If a quarter can be half of the last one, fixed costs are what turn a slow patch into an emergency.
  • Seasonal. Variable through the trough, fixed through the peak, as far as the labour market allows. This is the hardest one to execute and the most valuable to get right.
  • Early and unproven. Variable, almost regardless of the cost. You are buying the option to be wrong, and paying a premium per unit for it is a reasonable price.

Fixed-cost break-even

$1.05m

12% below current revenue

Variable-cost break-even

$780k

35% below current revenue

The trade

2.8x

upside, for that fragility

Free · no account · no card

Get your 2027 budget built from your QuickBooks — P&L, balance sheet and cash flow, in Excel.

Build my 2027 budget →

Most costs are more variable than they feel

Fixed and variable is a spectrum, not a switch, and much of it is a contracting decision rather than a fact of nature. Subcontractors instead of employees. Rented equipment instead of owned. Commission-weighted pay instead of salary. Cloud capacity instead of servers. Shorter leases at a higher rate.

Each converts a fixed cost into a variable one, and each costs more per unit. That premium is the price of flexibility, and it is worth paying exactly when you are uncertain — which is most of the time for a small business.

The direction of the ratchet

The dangerous pattern is drifting toward fixed without deciding to. It happens naturally: a contractor becomes an employee, a rental becomes a purchase, a rolling lease becomes a five-year one. Each step is individually sensible and slightly cheaper per unit.

Then a slow quarter arrives and none of it can be unwound. Reviewing your fixed-to-variable split once a year, alongside the annual plan, is enough to catch it — and the moment to add fixed costs is when revenue has become genuinely predictable, not when you merely hope it will be.

Cost structure is what sets your break-even and your margin of safety — the break-even calculator will show you how far revenue can fall before your current structure stops working.

Need your financials for a lender, a buyer or your accountant? Get the free financials pack →

See what an AI CFO says about your own numbers.

$99/mo, everything included. Free for 14 days, no card.

Meet your AI CFO →

Keep reading

Finance 101October 9, 2026 · 7 min read

What "profit" means on four different reports

Your P&L, your tax return, your bank balance and your valuation will all give you a different profit number for the same year. None of them is lying. Here's what each is measuring and which one to use for which decision.

Read it →
Finance 101October 3, 2026 · 7 min read

Contribution margin: the number that decides what to sell more of

Gross margin tells you about a product. Contribution margin tells you what one more sale is worth - and once overhead is in the mix, the two rankings disagree often enough to change what you push.

Read it →
Finance 101October 1, 2026 · 6 min read

Your year-end close starts in October

Everything that makes a year-end close painful is fixable in October and unfixable in January. Here's the work to front-load now, in the order that removes the most pain later.

Read it →
Finance 101September 29, 2026 · 6 min read

Budget, forecast, plan: three documents, three jobs

These three words get used interchangeably, and the confusion costs real money - because a business that only has one of them either can't hold anyone accountable or can't see what's coming. Here's what each is for and how they work together.

Read it →
Finance 101September 27, 2026 · 7 min read

Vendor terms: the cheapest financing you're not asking for

Moving a supplier from net 15 to net 45 is an interest-free loan you can arrange in one email. Here's what those thirty days are actually worth, when an early-payment discount beats holding the cash, and how to ask without damaging the relationship.

Read it →
Finance 101September 25, 2026 · 6 min read

Your break-even changes every time you hire

Adding a salary raises the sales floor you have to clear before you make a penny - and by more than the salary, because you only keep the contribution margin on each sale. Here's the number to run before you make the offer.

Read it →
Finance 101September 23, 2026 · 7 min read

Churn is a cash problem before it's a growth problem

Losing customers shows up in your growth rate months after it shows up in your bank account. Here's why churn is the most expensive number in a subscription or repeat-purchase business, and the ceiling it quietly sets on how big you can get.

Read it →
Finance 101September 21, 2026 · 7 min read

Seasonality: planning a business with an uneven year

If four months carry your year, annual averages will mislead you about every decision you make in the other eight. Here's how to plan, staff, and hold cash when the calendar is lumpy - and how to tell a bad month from a normal one.

Read it →
Finance 101September 19, 2026 · 7 min read

Estimated taxes: the bill nobody forecasts

Four times a year a large payment leaves your account and it appears on no budget, no P&L line, and no forecast. Here's why the tax bill catches profitable businesses off guard, and the simple mechanism that stops it.

Read it →