Wauvel
Finance 101

Payroll timing: the extra pay period nobody budgets for
← All posts
By Blake EkelundOctober 31, 2026 · 6 min read

Biweekly payroll means 26 pay dates a year. Except when it means 27, which happens roughly every eleventh year because 26 fortnights is 364 days and the calendar is not.

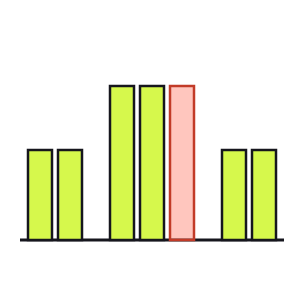
And regardless of the year, two months in every year contain three pay dates rather than two. If your budget divides annual payroll by twelve, those months arrive 50% over plan — and payroll is usually the largest line in the business.

The three-payroll month

With payroll of $84,000 a fortnight, a normal month costs $168,000. A three-payroll month costs $252,000. That is an $84,000 variance nobody caused, on a date that was knowable a year in advance.

Biweekly payroll across a quarter
MonthPay datesPayroll costvs monthly average
April2$168,000—
May3$252,000+$84,000
June2$168,000—
Quarter7$588,000On plan
The quarter is exactly on budget. One month inside it is $84,000 over, and the cash has to exist on that date regardless of what the monthly average said.

Which is right: 26 or 27?

Both, for different purposes, and confusing them is where the problem starts.

For cash, count actual pay dates. Put every one on the calendar and into the forecast on its real date. The money leaves when it leaves.

For expense, accrual accounting spreads it properly — wages are recognised as earned, so a month containing three payments does not report 50% more wage expense. If your P&L swings with pay dates, your payroll is being recorded on a cash basis and the monthly numbers are not comparable.

Pay periods

27

in roughly one year in eleven

Three-payroll months

2

every single year

The surprise

$84k

on a knowable date

Free · no account · no card

Get your 2027 budget built from your QuickBooks — P&L, balance sheet and cash flow, in Excel.

Build my 2027 budget →

What to do about the 27th period

In a 27-period year, annual payroll cost genuinely rises by about 3.8% for salaried staff — you are paying 27 fortnights of salary in a year budgeted for 26. That is a real cost increase and it needs to be in the plan.

There are ways to handle it and they have consequences worth thinking about. Some businesses simply absorb it as an extra payroll, which is cleanest and most expensive. Some recalculate the per-period amount so annual salary stays constant, which reduces every paycheque slightly and is usually unpopular. Anything that changes what people receive per period deserves a conversation with a payroll adviser and clear communication, well in advance.

Put every pay date on the forecast

This is the fix, and it is almost trivially simple. Payroll dates for the next twelve months are knowable today. Put them all on the 13-week cash flow as actual dated outflows rather than a monthly average.

The three-payroll month then stops being a surprise and becomes a constraint you plan around — and the collisions become visible too. A three-payroll month that also contains a quarterly tax payment and an annual insurance renewal is precisely the week a comfortable business ends up drawing on a line of credit, and none of the three components was unexpected on its own.

Every dated outflow belongs on the 13-week cash flow forecast — it is built weekly precisely so that timing like this shows up.

Need your financials for a lender, a buyer or your accountant? Get the free financials pack →

See what an AI CFO says about your own numbers.

$99/mo, everything included. Free for 14 days, no card.

Meet your AI CFO →

Keep reading

Finance 101November 12, 2026 · 6 min read

Commission plans that don't destroy your margin

Pay commission on revenue and you've asked your salespeople to discount. Pay on gross profit and the incentive points the same way your P&L does. Here's how to structure a plan that survives contact with a motivated seller.

Read it →
Finance 101November 10, 2026 · 6 min read

Setting next year's prices

Most small businesses don't set prices annually - they set them once and then react. Building a yearly price review turns an awkward negotiation into a routine, and stops three years of quiet cost absorption from eating your margin.

Read it →
Finance 101November 8, 2026 · 6 min read

The fixed asset register nobody keeps (and what it costs)

Most small businesses have a depreciation number their accountant produces once a year and nobody understands. A real asset register tells you what you own, what it's worth, what's fully depreciated, and what you'll have to replace next year.

Read it →
Finance 101November 6, 2026 · 7 min read

Holiday cash: managing the peak and the hangover

The dangerous part of a holiday season isn't the peak - it's February, when the inventory is paid for, the returns land, and the sales have stopped. Here's how to plan the whole arc rather than the good half.

Read it →
Finance 101November 4, 2026 · 7 min read

Working capital: why growing faster makes you poorer

Every dollar of new revenue drags cash into receivables and inventory before it comes back. That's why a fast-growing, profitable business can run out of money - and why there's a growth rate above which you cannot self-fund.

Read it →
Finance 101November 2, 2026 · 7 min read

Quality of earnings: what a buyer will normalize

Long before anyone values your business, they rebuild your profit from scratch - adding back what's yours personally and removing what won't repeat. Here's what that exercise finds, and why it's worth doing on yourself three years early.

Read it →
Finance 101October 25, 2026 · 7 min read

When to fire a product line

Dropping the worst-performing line often makes profit fall, because its allocated overhead doesn't leave with it. Here's the calculation that tells you whether killing something actually helps, and the costs that genuinely do disappear.

Read it →
Finance 101October 23, 2026 · 7 min read

Overhead allocation: charging costs to the jobs that caused them

If overhead is a lump nobody owns, every job looks more profitable than it is and the least efficient work looks the best. Here's how to push shared costs down to jobs without building a costing department.

Read it →
Finance 101October 21, 2026 · 7 min read

Deposits, retainers and progress billing: getting paid before you deliver

The cheapest working capital available to most businesses is their own customers, and the mechanism is billing structure rather than collections. Here's how deposits and progress billing change your cash curve - and how to book them correctly.

Read it →