Quality of earnings: what a buyer will normalize
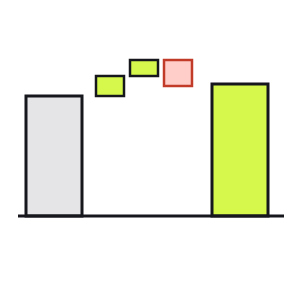
A buyer does not value the profit on your income statement. They value what the business would earn under a normal owner, with a market-rate manager, without your personal expenses and without whatever unusual things happened in the last three years.
Rebuilding that number is a quality of earnings analysis, and it is the single most consequential exercise in any sale. It is also entirely possible to run on yourself, years early, while there is still time to change the answer.
The two directions of adjustment
Add-backs raise the number: costs the business carries that a new owner would not. Your above-market salary, a family member on payroll, the vehicle, personal travel, one-off legal fees.
Adjustments cut the other way: costs the business does not carry but should. If you pay yourself nothing, a market wage for your role gets subtracted. If you have deferred equipment replacement for three years, a buyer prices in the catch-up.
| Amount | Why | |
|---|---|---|
| Reported net income | $186,000 | As filed |
| + Owner salary above market | $64,000 | You paid yourself $190k for a $126k role |
| + Personal expenses | $28,000 | Vehicle, travel, phone |
| + One-time legal | $41,000 | A dispute, genuinely settled |
| − Missing manager | $78,000 | Nobody runs it without you |
| − Deferred maintenance | $34,000 | Three years of catch-up |
| = Adjusted EBITDA | $207,000 | What is being valued |
Every add-back has to be provable
This is where owners lose money. An add-back you assert but cannot document gets rejected, and at a 4x multiple a rejected $40,000 add-back costs you $160,000 of purchase price.
"One-time" is the most contested word in the exercise. A legal settlement with a filed case behind it is defensible. "Unusual" costs appearing in each of the last three years are not unusual, and a buyer will say so. If you intend to add something back, keep the invoice, the contract, and a note explaining it, in the year it happens.
Free · no account · no card
Get your 2027 budget built from your QuickBooks — P&L, balance sheet and cash flow, in Excel.
The things that quietly reduce the multiple
Beyond the arithmetic, a buyer is assessing how risky the earnings are. The same $207,000 is worth materially different multiples depending on:
- Customer concentration. One customer at 40% of revenue is the single most common valuation discount, and often a deal breaker.
- Owner dependence. If the relationships, the pricing and the technical knowledge live in your head, the buyer is purchasing a job rather than an asset.
- Revenue that does not repeat. Contracted or recurring revenue is valued far above project work that has to be won again every year.
- Messy books. Every hour a buyer spends unpicking your accounts raises their sense of risk. Clean monthly statements with reconciliations behind them are worth real money.
Reported profit
$186k
what the P&L says
Adjusted EBITDA
$207k
what gets valued
One rejected add-back
-$160k
on price, at a 4x multiple
Do it on yourself, three years early
Almost everything that improves the number takes time. Reducing customer concentration takes a year or two of deliberate selling. Building a management layer so the business runs without you takes longer. Documenting add-backs only works if you did it as the costs occurred.
Run the analysis on your own numbers now, even with no intention of selling. It tells you what a buyer would pay, which is a useful proxy for what you have actually built — and every fix it suggests is a change that makes the business better to own in the meantime.
The version of this that goes badly is discovering, in the middle of a sale process, that three years of casual bookkeeping and one large customer have taken a third off the price. By then none of it is fixable.
Need your financials for a lender, a buyer or your accountant? Get the free financials pack →
See what an AI CFO says about your own numbers.
$99/mo, everything included. Free for 14 days, no card.