Which customers actually make you money
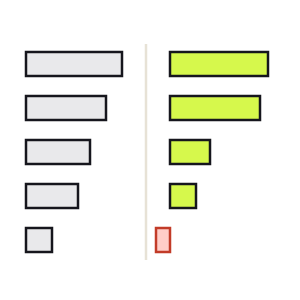
Every business has a customer ranking, and almost every business has the wrong one. Ask an owner to name their best customers and they will list the largest by revenue — because that is the only ranking their accounting system can produce.
Revenue is not profit, and customers do not consume your costs evenly. The one who pays on time, orders in bulk, and never calls is not the same business as the one with the same invoice total who wants custom work, rush shipping, three revisions, and pays in 70 days. Your P&L shows those two as identical. They are not remotely.
Push the obvious costs down first
You do not need an activity-based costing system. Start with the costs that are already traceable to a specific customer — most accounting systems can tag them and you can pull the rest from shipping and processing reports.
Revenue, then direct cost of what you delivered, then the customer- specific costs that usually get swept into overhead: shipping you paid, payment processing, returns and credits, discounts, and any support or service hours you can attribute. That alone reorders the list for most businesses, and it takes an afternoon rather than a project.
| Customer | Revenue | Direct costs | Contribution |
|---|---|---|---|
| A · steady wholesale | $186,000 | $132,000 | $54,000 |
| B · high-touch custom | $154,000 | $139,000 | $15,000 |
| C · bulk, pays early | $121,000 | $62,000 | $59,000 |
| D · rush orders, returns | $98,000 | $104,000 | -$6,000 |
| E · small, no service | $44,000 | $21,000 | $23,000 |
| Total | $603,000 | $458,000 | $145,000 |
Then add the cost of waiting
There is one more cost that almost never gets attributed and often should be: time. A customer who takes 75 days to pay is financing their business with your cash. If you are carrying a line of credit, that is a real interest expense with their name on it. If you are not, it is the opportunity cost of money you could not deploy.
A rough charge is enough to make the point. Take the average balance they owe you across the year and apply your cost of capital — your line rate, or 8–10% if you have nothing to borrow against. On a customer who carries $40,000 of your money for a year, that is $3,500 of profit that quietly belongs to them.
Contribution, customer D
-$6k
before financing cost
Average balance owed
$31k
at 74 days to pay
True contribution
-$8.7k
after cost of capital
Free · no account · no card
Get your 2027 budget built from your QuickBooks — P&L, balance sheet and cash flow, in Excel.
What to do with an unprofitable customer
Almost never fire them. That is the dramatic answer and it is usually the wrong one, because a customer covering some of your fixed costs is better than an empty slot — unless the slot is genuinely full.
The finding is a negotiating position, not a verdict. Work through the options in order of how little damage they do:
- Reprice the thing that costs. Not the whole relationship — the specific driver. Charge for rush shipping, bill for revisions past the second, set a minimum order.
- Change the terms. A customer who is marginal at 75 days may be fine at 30. Moving payment terms is often easier to sell than a price increase, and it fixes the financing cost directly.
- Change how you serve them. Much of the cost is often service you have offered rather than service they require. Ask what they would give up before assuming they need all of it.
- Then, and only then, let them go. If the answer is no to all of the above and your capacity is genuinely constrained, the slot is worth more filled with someone else.
Look at the top of the list too
The unprofitable customer gets all the attention, but the more valuable finding is usually at the other end. Customer C in the table above contributes more than A on a third less revenue — because they buy in bulk, need no service, and pay early.
That is a profile. Whatever your sales and marketing effort looks like next quarter, it should be aimed at finding more of them. Most businesses market to everyone, discover their best segment by accident, and never notice it because the only ranking they ever see is by revenue.
Need your financials for a lender, a buyer or your accountant? Get the free financials pack →
See what an AI CFO says about your own numbers.
$99/mo, everything included. Free for 14 days, no card.